Personal Loans in Maryland: What Licensed Lenders May Charge
Maryland caps consumer loans with monthly rates in the Consumer Loan Law, and the lowest of them apply to anything over $2,000. Here is how the limits work, who needs a consumer lender license, and where to check a lender.
Cap 36% or less, by LendCedar Editorial Team Updated 5 minute read
In short
Maryland's Consumer Loan Law, Commercial Law section 12-306, sets monthly rate limits. For a loan of $2,000 or less, a licensed lender may charge up to 2.75% a month (33% a year) on the unpaid balance up to $1,000 and 2% a month (24%) above $1,000. For a loan over $2,000, the limit is 2% a month on the unpaid principal balance. A lender making these loans needs a consumer lender license from the Office of Financial Regulation (OFR). The National Consumer Law Center puts the ceiling at about 30% APR on a $2,000 two-year loan and about 25% on a $10,000 five-year loan.
- $2,000 loan cap
- 30% APR
- $10,000 loan cap
- 25% APR
- Loans over $2,000
- 2% a month (24%)
- Licensed by
- Maryland OFR
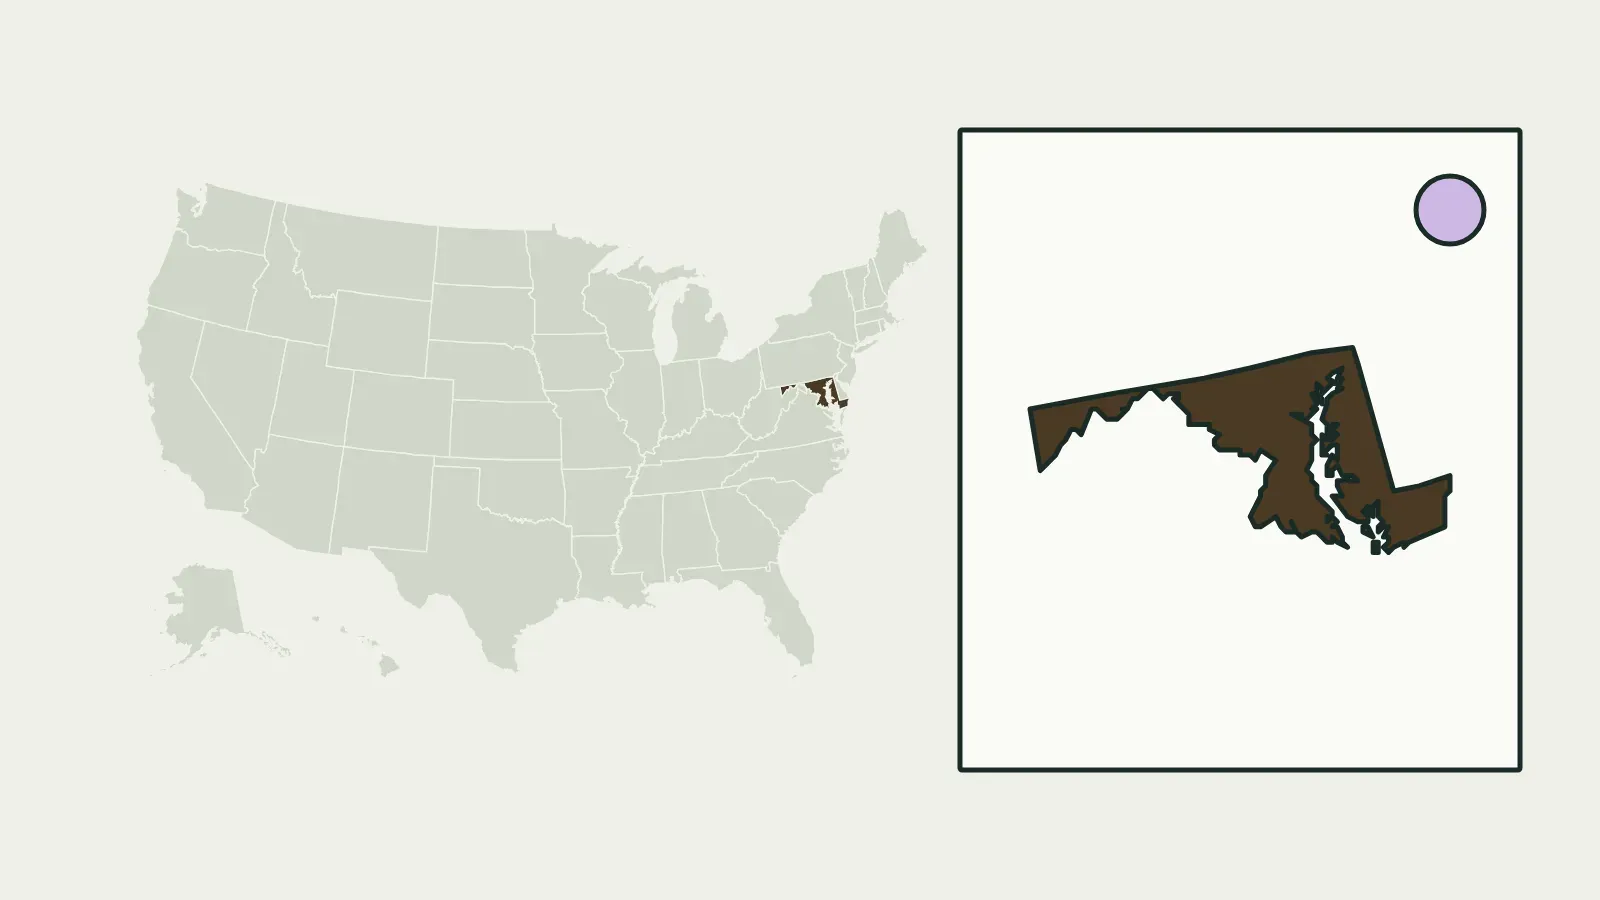
Maryland at a glance
How the Maryland rate limit works
Section 12-306(a) keeps two schedules. The older one, with several brackets, dates from before July 1, 1982. Loans made on or after that date may use the simpler schedule below, as long as the loan has no balloon payment (unless payment in full is due on demand or within a year) and meets the code's rules on refinancing, adjustable rates and repossession.
| Loan size | Part of the balance | Maximum rate |
|---|---|---|
| $2,000 or less | Up to $1,000 | 2.75% a month (33% a year) |
| $2,000 or less | Above $1,000 | 2% a month (24% a year) |
| Over $2,000 | Whole unpaid principal | 2% a month (24% a year) |
To see how the brackets add up, take a $1,500 balance on a small loan. The first $1,000 may carry 33% a year ($330) and the other $500 may carry 24% ($120), or $450 a year, a blended 30% at the start. On a $5,000 loan the limit is 24% on the whole balance, or $1,200 in the first year. These figures illustrate the limit; they are not offers.
The older schedule is lower in places: for loans of $2,000 or less, 2.75% a month up to $500, 2% from $500 to $700 and 1.25% above $700; for larger loans, by original principal, 1.75% a month on loans up to $3,500, 1.5% on loans up to $5,000 and 1.35% on loans above $5,000. The same section bars a lender from taking interest in advance or compounding it. Because the APR on your Truth in Lending disclosure counts the finance charge as a yearly rate, you can set it directly against these limits.
How Maryland compares with its neighbors
On the National Consumer Law Center's comparison of a $2,000 two-year loan, Pennsylvania and Washington, D.C., cap the loan at about 24% APR and West Virginia at about 33%, while Virginia allows about 50%. Delaware sets no numeric cap. If you live near a state line, your state of residence and the lender's license decide which rules apply. The state rules map shows every state side by side.
Who needs a license and who does not
A business that makes any loan or advance of money or credit under the Maryland Consumer Loan Law (Commercial Law section 12-301 and following) needs a consumer lender license under Financial Institutions Article, Title 11, Subtitle 2. The OFR, part of the Maryland Department of Labor, issues it through NMLS. Since July 1, 2023, one license covers the principal office, and other locations operate under it once they are disclosed to the Commissioner.
- Installment loan lenders hold a separate OFR license; a consumer lender licensee does not need it to make certain non-mortgage loans.
- Banks and credit unions answer to separate charters and regulators, and a bank may charge the rates its home state allows. Online lenders that partner with a bank may lend through that bank, so ask who the lender of record is.
- Payday and title loans are covered by our sister site Lendmira on its Maryland lending laws page.
If a lender asks for a fee before it will approve or fund a loan, treat that as a warning sign; how to verify a lender explains what to check.
Check a lender and file a complaint
- Look up the license in the OFR license search or on NMLS Consumer Access before you apply.
- Keep the loan papers: the Truth in Lending disclosure, the agreement and any messages about fees.
- File a complaint with the OFR by following its complaint instructions online, or call its Consumer Response Unit at 410-230-6077, which can also tell you whether it regulates a provider.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
Sources
- Md. Code, Commercial Law section 12-306, Interest (Maryland General Assembly)
- Consumer Lenders (Maryland Office of Financial Regulation)
- How to file a complaint (Maryland Office of Financial Regulation)
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. The statute states its limits as monthly rates; the yearly figures in parentheses are those rates times 12.
Questions people ask
What is the maximum interest rate on a personal loan in Maryland?
For a loan made by a licensed lender under Commercial Law 12-306, up to 2.75% a month (33% a year) on the balance up to $1,000 and 2% a month (24%) above $1,000 for loans of $2,000 or less, and 2% a month on the whole balance for loans over $2,000.
Who licenses personal loan companies in Maryland?
The Office of Financial Regulation in the Maryland Department of Labor issues consumer lender licenses under Financial Institutions Article, Title 11, Subtitle 2.
Do the Maryland limits apply to banks?
Banks and credit unions follow their own charters and federal law, and a bank can charge the rate allowed in its home state. The section 12-306 limits bind lenders making loans under the Consumer Loan Law.
How do I check a Maryland lender?
Search the company in the OFR license search or on NMLS Consumer Access. See how to verify a lender for the other checks.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Total cost of a loan
Finance charge, APR and total of payments, with three worked offers for the same $10,000 loan.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Offer term
Truth in Lending disclosures
The federal box line by line: APR, finance charge, amount financed, total of payments and what sits below.